

Jim: sell & get paid instantly
by CloudWalk
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
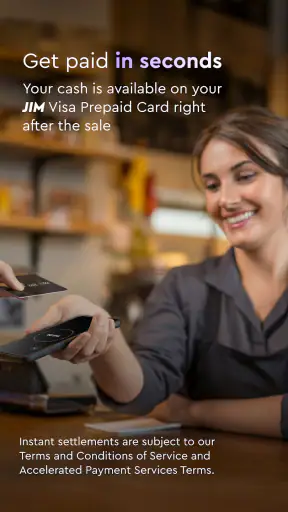
 Analysis by Getfullapps
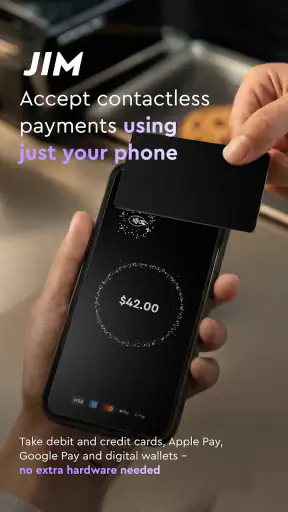
I tried Jim: sell & get paid instantly as a finance app for accepting card payments through a phone, and its appeal is immediately clear: it is aimed at people who want to sell without carrying a separate card terminal. That makes it more interesting than a typical budgeting or banking app, because the phone becomes part of the checkout process rather than just a place to view transactions.
The app is developed by CloudWalk and is free to install. It is available to users aged Everyone, supports Android 7.0 and later, and the current version is 1.4.19. Those details make it accessible to a broad range of Android phones, including older devices that may not run many newer finance tools comfortably. The store listing shows a 4.4 average from around 2.2 thousand ratings, with over 100 thousand installs, so there is already a meaningful group of people trying it.
How Jim fits into everyday selling
The most useful way to understand this app is to picture a small transaction away from a traditional checkout. I might be selling at a local event, taking an order during a home visit, or delivering something directly to a customer. Instead of asking for cash or relying on a separate reader, I can use my phone as the payment point. That is a very different role from the usual personal finance app, and it gives Jim a focused purpose.
The promise is not simply convenience for the seller. A customer who does not have cash can still pay at the moment the sale happens, while the seller avoids sending someone away to find an ATM or postponing payment until later. For occasional sellers, that can be the difference between completing a sale and losing it.
I also like the portability of the idea. A fixed checkout setup makes sense for a shop with a permanent counter, but it is excessive for someone who sells in several places. Jim is better suited to a phone-first workflow: open the app when needed, use the phone at the point of sale, and keep the transaction tied to the device already in your hand.
That said, I would not treat the app as a complete replacement for every payment setup. A dedicated terminal can still be more comfortable during a busy period, especially when several customers are waiting. The phone-based approach is strongest when flexibility matters more than a full retail checkout experience.
What the free price really means
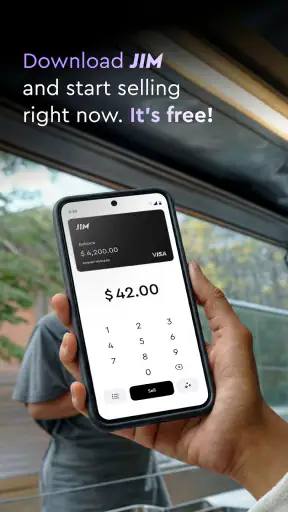
Jim is listed as free, which removes the first barrier to trying it. I do not have to buy the app before deciding whether its selling workflow suits me, and a small seller can explore the concept without committing to software costs up front. That is a meaningful advantage over any solution that requires a paid download simply to test the basic experience.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
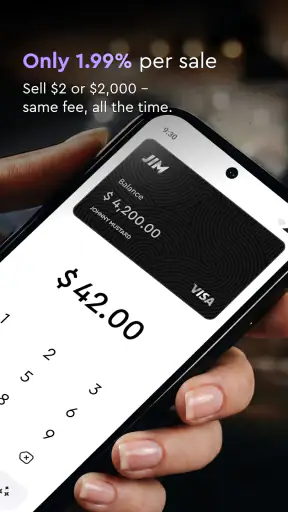
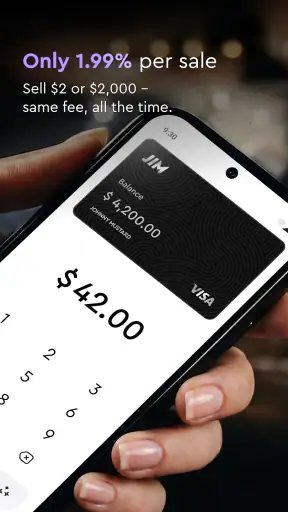
Free access should not be confused with free payment processing. The app’s listed price tells me that downloading and using the application does not require a purchase, but it does not establish every possible cost connected with accepting payments. I would check the terms shown during setup and before relying on it for regular business income. This distinction matters: the value of the app is its accessible entry point, while the cost of individual transactions is a separate question.
For a person who only sells now and then, free access makes experimentation sensible. I can see whether my phone, selling routine, and customers fit the approach before investing in equipment. For a busy business, however, I would judge the complete payment economics rather than stopping at the download price. A free app can still be a poor choice if its transaction conditions do not fit the business.
The workflow I would use before accepting a payment
My first practical step would be to install Jim on the phone I actually plan to use at a sale, not on a spare device sitting at home. The point is to test the complete routine under realistic conditions: the phone’s screen, battery, network connection, and how quickly I can move from opening the app to presenting a payment request.
I would also prepare the phone before a selling session. That means charging it, closing distracting applications, and making sure the device is not likely to lock at the exact moment a customer is ready to pay. These are small details, but a phone functioning as a card reader has a different responsibility from a phone used for messages or browsing.
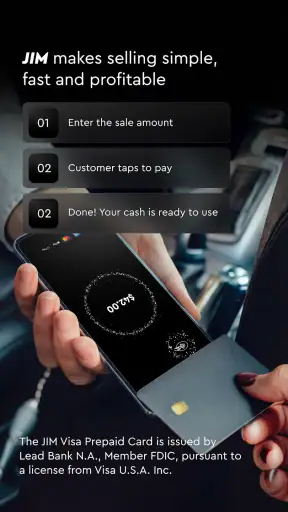
A useful habit is to separate the payment moment from the rest of the sale. I would confirm the item and amount first, then enter or present the payment request, and finally wait for a clear completion state before handing over the product. This reduces the risk of confusing an attempted payment with a completed one. The app may make the transaction fast, but speed should not replace verification.
I would keep a simple backup plan as well. That could mean accepting another payment method or recording the customer’s order while the connection is restored. A phone-based reader is convenient precisely because it depends on a phone, so the seller should plan for the ordinary problems that affect phones: low battery, poor signal, notifications, or accidental screen locks.
Where the app delivers real value
The strongest value is mobility. A market seller can move between tables, a service provider can collect payment after finishing a job, and a small creator can accept payment during a temporary event without arranging a permanent checkout counter. In each case, the phone is already the tool being carried, and Jim adds a selling function to it.
Another benefit is reducing equipment clutter. Someone starting a small side business may not want a separate reader, cables, or a dedicated checkout station immediately. The app offers a way to explore card acceptance with less physical setup. That does not guarantee that it will be the best long-term system, but it lowers the practical hurdle for getting started.
I see particular value for sellers whose payment needs change from day to day. A permanent shop generally has predictable traffic and can justify a more elaborate system. A mobile tutor, repair worker, independent stylist, or occasional event vendor may need payment acceptance only at certain moments. For those users, portability is not a minor feature; it is the reason to consider this app.
The app can also make a seller look more prepared in situations where cash is inconvenient. Customers increasingly expect to pay electronically, and being able to handle that request at the point of sale can make a small operation feel smoother. I would still avoid overselling this benefit: a professional appearance comes from reliable execution, not merely from having the app installed.
Tradeoffs that matter before relying on it
The first tradeoff is the phone itself. A separate terminal is designed around payment handling, while a smartphone has many competing functions. Calls, alerts, battery-saving settings, and a crowded screen can all interrupt the flow. Jim’s phone-first design is convenient, but it also means the seller must manage the device carefully.
The second is comfort during repeated transactions. For one or two sales, using a phone may feel effortless. During a long, busy session, a dedicated reader or full checkout system may be easier to operate repeatedly. If my business depends on a steady queue, I would compare the physical handling experience rather than choosing solely because the app is free.
There is also a learning curve for customers. Some people will understand the process immediately, while others may need a moment to follow what the phone is asking them to do. I would leave enough space for the customer to see the payment interaction clearly and would avoid rushing them. A fast payment tool still needs a clear human explanation when the situation is unfamiliar.
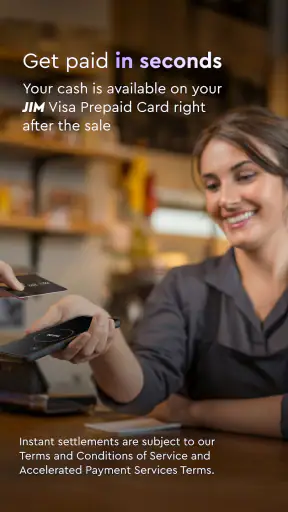
Reliability is another practical concern. The store summary emphasizes getting paid in seconds, but real-world speed can depend on the phone, connectivity, and the customer’s payment method. I would test Jim in the places where I intend to sell instead of assuming that a smooth home test guarantees the same result at an outdoor event or a busy location.
Finally, I would not use a payment app as my only business record. Jim may handle the payment interaction, but I would maintain my own basic sales notes for orders, refunds, stock, and customer commitments. That separation is especially useful for sellers who grow beyond occasional transactions. Payment acceptance and business administration are related, but they are not the same task.
Who should try it first
Jim makes the most sense for a small seller who values portability and wants to avoid buying equipment before understanding their payment volume. It is also a reasonable starting point for someone whose sales happen in changing locations rather than at one permanent counter. The free download gives that user room to test the idea without paying for the application itself.
I would recommend trying it with a controlled, low-pressure sale first. A friend, a familiar customer, or a quiet appointment is better than making the first ever attempt during the busiest moment of an event. That trial can reveal whether the phone is comfortable to use, whether the payment flow is easy to explain, and whether the seller feels confident recognizing a completed transaction.
It may also suit service providers who finish work away from a shop. A person who visits customers can carry one phone instead of adding a separate payment device to every appointment. The advantage is greatest when the seller already has a clear amount to charge and wants to complete payment before leaving.
I would be more cautious for a high-volume retailer, a team with several cashiers, or a business that needs detailed inventory and staff controls. Those users may be better served by a complete point-of-sale system or a dedicated terminal, even if that option costs more. Jim’s value comes from focused mobility, not from replacing every business tool.
It is also not the right choice for someone who only wants to track personal spending. This is a selling and payment-acceptance app, not a general budgeting companion. Installing it will not add much value if I have no need to receive card payments from customers.
Questions I would settle before launch day
Can I use it on my current phone? The minimum operating system is Android 7.0, so many older Android phones are within the supported range. Still, compatibility on paper is only the starting point. I would install it on the exact device intended for sales and perform a complete test, because screen size, battery condition, and connectivity can affect the experience even when the operating system is supported.
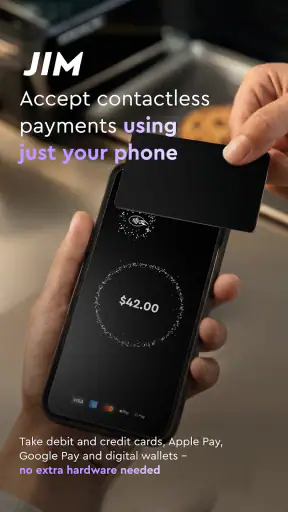
Do I need extra hardware? The central idea is that the phone acts as the card reader, so the attraction is avoiding a separate reader in the basic setup. I would nevertheless follow the app’s own setup instructions carefully and confirm what the payment interaction requires in my situation. The important practical question is not just whether the app installs, but whether my phone can complete the customer-facing step comfortably.
Will money arrive instantly every time? I would treat the wording as the intended speed of the service, not as a reason to skip checking the result. During a real sale, I would wait for the app to show completion and keep my own record of the order. If a transaction appears delayed or unclear, I would not hand over a valuable item based only on a customer’s assumption that payment went through.
Is the free price enough to make it the cheapest option? No. Free installation is a strong advantage, but the overall value depends on the conditions attached to payment processing and on whether the workflow saves enough time and equipment cost for my business. I would compare those practical terms with a traditional reader or a larger point-of-sale service before making it the main payment method.
Can it handle my whole business? I would answer that conservatively. Jim is compelling as a mobile way to accept payments, but I would still use separate methods for stock, invoices, customer details, and tax records unless the app clearly covers those needs in my setup. Keeping those jobs distinct prevents disappointment and makes the app easier to evaluate on its actual strength.
My comparison with the usual alternatives
Compared with cash, Jim offers a way to serve customers who do not carry notes or coins, and it can reduce the need to prepare change. Cash remains useful as a backup because it does not depend on a phone battery or mobile connection in the same way. I would see Jim and cash as complementary options for a small seller rather than assuming one completely eliminates the other.
Compared with a traditional card reader, the main difference is equipment. Jim’s phone-based approach is attractive when I want to travel light or test a new side business. A separate reader may feel more purpose-built and predictable during repeated sales. The better option depends on whether my priority is low setup friction or dedicated hardware for a steady operation.
Compared with a full point-of-sale platform, Jim appears more focused. A larger system can be preferable when I need staff accounts, inventory controls, receipts, reporting, and a permanent checkout routine. I would choose Jim when payment mobility is the central problem, not when I am searching for an all-in-one business-management suite.
The app’s 4.4 average and growing install base make it worth investigating, but they do not decide the choice for me. Payment tools are unusually dependent on personal workflow. A seller should test the exact phone, location, customer interaction, and record-keeping routine rather than relying on popularity alone.
My verdict for different kinds of sellers
For an occasional seller, Jim is an easy app to consider because it is free to install and directly addresses a practical problem: accepting card payments without carrying a conventional reader. I would try it before buying equipment, especially if sales are irregular or take place in several locations.
For a growing business, I would use it as a trial or a mobile payment option while comparing it with more complete systems. The app can be useful at temporary events or during visits, but a busy operation may eventually value dedicated hardware and deeper business controls more than the convenience of using one phone.
For a personal user with no customers, I would skip it. Its purpose is specific, and there is little reason to add a selling tool to a phone that is not being used for sales. Choosing an app because it is free is not the same as receiving value from it.
My overall view is favorable but practical. Jim is most valuable when mobility, low initial commitment, and phone-based card acceptance matter more than a full retail setup. I would download it, test it with a small transaction, review the payment conditions carefully, and keep a backup method ready. If that trial feels natural, the app can be a smart fit for independent sellers. If I were running a busy counter or needed complete business management, I would look toward a dedicated reader or broader point-of-sale solution instead.
CloudWalk has positioned this finance app around a clear use case rather than trying to make it a universal money tool. That focus is its strength. It does not need to replace every alternative to be useful; it only needs to make mobile selling reliable enough for the people it targets. In my experience, that makes it worth testing, provided I judge it by the full payment workflow and not by the free download alone.
Pros
- Instant payment options help sellers access funds quickly.
- Simple listing tools make it easy to upload and sell items.
- Built-in messaging supports direct communication with buyers.
- Useful for local selling without complicated store setup.
- Mobile notifications help users respond to offers promptly.
Cons
- Availability and features may vary by country or region.
- Transaction fees can reduce the final amount sellers receive.
- Some buyers may expect quick replies and immediate availability.
- Local marketplaces may have limited activity in smaller areas.
- Users should verify buyers carefully before completing transactions.
FAQs for Jim: sell & get paid instantly
What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a marketplace app designed to help users list items for sale, communicate with potential buyers, and receive payment through the platform. It is intended to make local or direct selling more convenient by bringing product listings, buyer conversations, and transaction details into one mobile experience. Available features may vary by location and account type.
How do I sell an item using Jim?
To sell an item, you generally create an account, upload clear photos, add a title and description, choose an appropriate category, and set your asking price. Before publishing, check the listing carefully for accurate condition, availability, and delivery or collection details. Good photographs and an honest description can improve buyer confidence and help prevent misunderstandings after the sale.
Do I get paid instantly after selling an item?
The app’s name highlights fast payments, but the exact timing can depend on the payment method, buyer confirmation, identity checks, account status, and local banking rules. Some transactions may be available quickly, while others can require processing or verification. Always review the payment terms shown in the app, and do not hand over an item based only on an unverified payment message.
Is Jim safe to use for buying and selling?
Jim can provide useful tools for managing listings and payments, but users should still follow normal marketplace safety practices. Keep conversations and transactions inside the official app whenever possible, verify payment status directly in your account, and be cautious of requests for codes, passwords, or extra fees. For in-person exchanges, choose a public location and inspect the item before completing the deal.
Are there fees or requirements for using Jim?
Fees, seller requirements, withdrawal limits, and supported payment options may differ according to your country, the type of transaction, and the current version of the service. Some features may require identity verification or a linked payment account. Before listing or accepting an offer, open the relevant pricing and terms information in the app so you understand any commission, delivery charge, or processing cost.

Jim: sell & get paid instantly
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@jim.com, visit https://jim.com, or review their https://www.jim.com/behind-the-curtain/privacy-agreements.










